所屬科目:研究所、轉學考(插大)◆統計學
1. Consider the simple linear population model without intercept: $y_i = \beta x_i + \varepsilon_i$$\varepsilon_i = \rho \varepsilon_{i-1} + u_i,$ where $u_i \sim i.i.d(0, \sigma^2)$. We use OLS method to estimate parameter $\hat{\beta}$. After we obtain the $\hat{\beta}$, we use OLS residuals to generate Durbin-Watson statistic. Which approximation value does Durbin-Watson statistic converge under $T \to \infty$? (A) \( 2 - \hat{\rho} \) (B) \( 1 - 2\hat{\rho} \) (C) \( 2(1 - \hat{p}) \) (D) \( 1 - \hat{p} \) (E) \( 2 - 3\hat{p} \)
2. Eric estimates a regression model as below: \( y_t = \alpha + \beta_1 x_t + \beta_2 z_t + u_t, \)Where\( u_t \sim N(0, \sigma_u^2) \).. If Eric regress $x_i$ on $z_i$, he find the following equation statistically significant: $x_i = \omega + \delta_2 z_i + \varepsilon_i.$Which problem he will face when he use OLS method to estimate $\hat{\beta}_1$ and $\hat{\beta}_2$? (A) Multicollinearity (B) Serial correlation (C) Heteroskedasticity (D) Nonlinear in parameter (E) Random sample
3. Mary want to estimates a regression model as below: $y_i = \alpha + \beta_1 x_{1i} + \beta_2 x_{2i} + \varepsilon_i,$ If she doubts the regression residuals $\hat{\varepsilon}_i$ with heteroskedasticity, she wants to use Breusch-Pagan test to detect whether heteroskedasticity exists in $\hat{\varepsilon}_i^2$. Which independent variables set she will choose to execute Breusch-Pagan test? (A) \( x_{1i}, x_{2i} \) (B) \( x_{n}, x_{2n}, x_{1n}^{2}, x_{2n}^{2} \) (C) \( x_{n}, x_{2n}, x_{1n}^{2}, x_{2n}^{2}, x_{1n} x_{2n} \) (D) \( x_{n}, x_{2n} \) (E) \( x_{n}, x_{2n}, x_{1n} x_{2n} \)
4. Consider the simple regression $y_i = \alpha + \beta x_i + \varepsilon_i$And suppose population parameter $\beta = 2$ and least square estimator $\hat{\beta} = 2.3$. Now consider the regression $(x_i - y_i) = \alpha^* + \beta^* x_i + u_i.$What is the value of \( \hat{\beta} \)? (A) 1 (B)-1 (C)-1.3 (D)-0.3 (E) 0.3
5. Consider the linear model with intercept: $y_t = \alpha + \beta x_t + u_t$ If the $A = \sum_{i=1}^{n} (x_i - \bar{x})^2$ is positive definite and $E(u_i \mid x_i) = 0, \forall t = 1, 2, \dots, T$, which statement is true under sample size $T \to \infty$. (A) \( \hat{\beta} \) is consistent, but we cannot judge whether \( \hat{\beta} \) is efficiency (B) \( \hat{\beta} \) is unbiased and efficiency (C) \( \hat{\beta} \) is consistent and efficiency (D) \( \hat{\beta} \) is, but we cannot judge whether \( \hat{\beta} \) is efficiency (E) \( \hat{\beta} \) is unbiased and consistent.
6. Consider the linear population model with intercept:$y_t = \alpha + \beta x_t + \varepsilon_t$The variance structure is known as below: $E(\varepsilon_t^2) = \sigma^2 h_t^2,$Which regression may obtain efficiency $\hat{\beta}$ estimator? (A) Regress \( y_{t} \) on 1, \( x_{t} \) (B) Regress \( y_{t} / h_{t} \) on 1/ht ,xt/ht(C) Regress \( y_{t} / h_{t}^{2} \) on 1/h2t ,xt/h2t(D) Regress \( y_{t} \) on 1/ht ,xt/ht(E) Regress \( y_{t} / h_{t} \) on 1, \( x_{t} \)
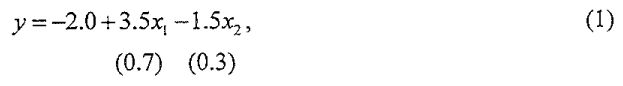
II、計算問答題(每大題 10 分,共 20 分。) 1. Mary has T = 40 observations on variables y, $x_1$, and $x_2$. She estimates the following equations by least squares: Residual sum of squares (SSR)=140, $R^2 = 0.8$ where the numbers in parentheses are standard errors. What is the true value of SST in equation (1)? What is the value of $s^2$ (estimated error variance.)?
(a). Consider the estimator \( \tilde{\beta} \). Whether is \( \tilde{\beta} \) unbiased?
(b). Compared with OLS estimator \( \hat{\beta} \), which estimators is efficiency? Please explain.
Ⅲ、填空題(每格 5 分,共 50 分。) 1. Let random variable X follow a geometric distribution with parameter p, that is, $P(X=x) = pq^{n-1}, \quad p+q=1, \quad x=1, 2, 3, \dots$ Calculate the probability of P(X > m), where m is a positive integer. (1)
2. Suppose $S_n = X_1 + X_2 + \dots + X_n$, where $E(X_i) = \frac{1}{n}$, $Var(X_i) = \frac{1}{n} - \frac{1}{n^2}$ and $Cov(X_i, X_j) = \frac{1}{n(n-1)} - \frac{1}{n^2}$ for $i \neq j$. Then, $Var(S_n) =$ (2) .
3. Suppose that the probability density function of X is $f(x) = 2x \exp(-x^2)$, $0 \le x < \infty$. Find the probability density function of $Y = X^2$, f(y) = (3) .
4. Suppose that the continuous random variables (X, Y, Z) have a valid joint probability density function $f(x, y, z) = Kxyz^2, \quad 0 \le x, y \le 1, \quad 0 \le z \le 3.$ Then, E(Y) = (4) and $E(Y|X = \frac{1}{2}, Z = 1) =$ (5) . Of course, you should find the value of K first.
5. If random variables $X_1, X_2, \dots, X_n$ are i.i.d. $N(\mu, \sigma^2)$, and $S^2$ is their sample variance. Then, the distribution of $\frac{(n-1)S^2}{\sigma^2}$ is (6) .
6. Suppose you play a game of chance where you win w dollars with probability p but lose v dollars with probability 1-p. Denote $X_i$ the random variable. Then, how large should p be so that you, a reasonable person, are willing to play the game? (7)
7. Let $X_1, \dots, X_n, X_{n+1}$ be a random sample from a normal population having an unknown mean $\mu$ and variance 1, and $\bar{X}_n$ be the average of the first n variables. Then, the distribution of $X_{n+1} - \bar{X}_n$ is (8) . If $\bar{X}_{200} = 5$, then the 95% confidence interval for $X_{201}$ is (9) .
8. In a multiple linear regression, a dependent variable is explained by a constant and 4 independent variables using 35 observations. The $R^2$ of this regression is 0.6. To test the significance of this regression, we can obtain the F statistic equal to (10) .
 阿摩線上測驗
登入