所屬科目:研究所、轉學考(插大)◆財務管理
1. 說明二項資金分離理論並說明其與資本市場線的關係(8分)
2. 請說明 Fama 提出的三種效率市場並且各自提出一種市場異常現象反駁效率市場假說(7分)
3. (1) 敘述「代理問題 (Agency Problems)」之意義。(4分)
(2) 「代理問題」會引發哪些成本?(4分)
4. 請說明如何形成效率前沿並且從而形成資本市場線(7分)
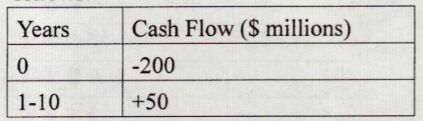
5. Epsilon Corp. is evaluating an expansion of its business. The cash-flow forecasts for the project are as follows:The firm's existing assets have a beta of 1.2. The risk-free interest rate is 4% and the expected return on the market portfolio is 12%. What is the project's NPV? (8分)
(1) A stock whose return is uncorrelated with all three factors.
(2) A stock with average exposure to each factor (i.e., with b=1 for each).
(3) A pure-play energy stock with high exposure to the energy factor ( b =2) but zero exposure to the other two factors.
(4) An aluminum company stock with average sensitivity to changes in interest rates and GDP, but negative exposure of b = -1.6 to the energy factor. (The aluminum company is energy-intensive and suffers when energy prices rise.)
7. 2015 年聯合國 195 個成員國於氣候高峰會中通過的「巴黎協定」(Paris Agreement),且金融穩定協會(Financial Stability Board)也制訂氣候攸關之財務風險揭露準則(Task Force on Climate-related Financial Disclosures, TCFD)。碳排放是導致氣候變遷的關鍵因素,我國金管會順應國際趨勢,於 2022 年頒布聚焦於碳排放盤查之「上市櫃公司永續發展路徑圖」,同時於 2023 年推動「永續投資生態圖」,希望擁有龐大資金的金融機構落實永續投資(Sustainable Investment),促進我國企業及環境之永續發展。學術上發現金融機構的確能藉由永續投資促使企業減少碳排放。例如刊登於全球第 2 名財務學術期刊(Journal Financial Economics, JFE)的文 Azar, Duro, Kadach, and Ormazabal (2021)- The Big Three and corporate carbon emissions around the world. 即提供了強而穩健的證據。此文摘要為:「This paper examines the role of the "Big Three" (i.e.,BlackRock, Vanguard, and State Street Global Advisors) on the reduction of corporate carbon emissions around the world. Using novel data on engagements of the Big Three with individual firms, we find evidence that the Big Three focus their engagement effort on large firms with high CO₂ emissions in which these investors hold a significant stake. Consistent with this engagement influence being effective, we observe a strong and robust negative association between Big Three ownership and subsequent carbon emissions among MSCI index constituents, a pattern that becomes stronger in the later years of the sample period as the three institutions publicly commit to tackle Environmental, Social, and Governance (ESG) issues.」請以中文翻譯上述摘要。(10分)
(1) 為何流動比率越高的公司,其速動比率不見得越高?
(2) 為何流動比率高的公司不一定能讓短期債權人安心?
(3) 為何股票投資人要關注公司之償債能力?
(4) 捷安特公司2021年的稅後淨利高達87億元,折舊與攤提為19億元,應收及應付票據及款項變動幅度不大,但當年之「來自營運之現金流量」卻為-49億元,請問其原因為何?
(5) 就一家優質公司而言,在其現金流量表中的三類現金流量中,通常其來自哪一類之現金淨流量為負?來自哪一類之現金淨流量為正?
(6) 為何總資產周轉率高的公司其固定資產周轉率不一定比較高?
(1)利息保障倍數
(2)每股盈餘(元)
(3)本益比(倍)
(4)營業利益率(%)
(5)每股帳面價值(元)
(6)每股現金股利(元)
(7)盈餘保留率(%)
(8)市場附加價值(10億元,Market Value Added)
(1) 請以中文簡要說明 Modigliani and Miller 之 資本結構無關論 的定理 1: Proposition 1: Firm value is determined on the left-hand side of the balance sheet by real asset — not by the proportions of debt and equity securities issued to buy the assets. (2) Modigliani and Miller 之資本結構無關論的 Proposition 2 : The expected rate of return on the common stock of a levered firm increases in proportion to the debt-equity ratio. 此定理之意含可具體化為:$r_E = r_A + (r_A - r_D) \frac{D}{E}$,請依據上式,分析公司增加舉債可能導致 $r_E$ 上升及下降的原因。
(3) 當公司增加舉債符合可以提升 $r_E$ 之條件時,卻不一定能提升公司之股票價值?(請分別由 Dividend Discounted Model 之分子及分母分析)
(4) 請寫出財報分析中的 DuPont analysis(杜邦方程式),說明增加舉債對一家淨利為負的公司之 ROE($r_E$)的影響。
(5) 影響公司舉債節稅金額,除了舉債金額之外,主要還有哪兩個因素?
(6) 公司增加舉債通常會導致下式等號右邊之四項成分中的哪幾項上升?哪幾項下降? $r_A = \left( r_D \times \frac{D}{D+E} \right) + \left( r_E \times \frac{E}{D+E} \right)$
 阿摩線上測驗
登入